
An 81-year-old pensioner in Valencia must pay 101,102.53 euros in back taxes after depositing 200,480 euros in cash he kept at home, judges have ruled. The regional court rejected his claim that the money came from decades of accumulated personal savings, finding he had failed to prove the specific origin of the bank notes.
The High Court of Justice of the Valencian Community upheld the tax reassessment on the deposit, which tax inspectors treated as an unjustified capital gain. However, the magistrates threw out a separate fine of 68,532.42 euros, ruling that tax authorities had not proved the pensioner acted with deliberate culpability.
Cash deposit and tax inspection
On 6 April 2017, the 81-year-old deposited 200,480 euros in physical cash into a bank account. He later explained to officials that he had stored the money at his home over many years because he did not trust banking institutions.
According to court documents, the pensioner decided to deposit the cash because he intended to lend the funds to his daughter to assist her in purchasing a property during a judicial proceeding.
The large cash deposit triggered an immediate verification check by the Agencia Tributaria, Spain's national tax administration agency. In his 2017 personal income tax return, the pensioner had declared 24,625.58 euros in earned income from his retirement pensions, alongside 2,041.37 euros from a small agricultural activity.
Because the retiree could not demonstrate an immediate declared source for the 200,480 euros, tax inspectors incorporated the full amount into his general taxable base for the 2017 tax year as an unjustified capital gain. That assessment generated a tax liability of 101,102.53 euros, in addition to a fine of 68,532.42 euros.
Documentary evidence and past sales
The pensioner contested the tax assessment, arguing that the cash did not represent new or untaxed income, but rather legitimate money saved from transactions conducted many years earlier. To support his defense, he provided tax authorities with extensive documentation of past assets and banking records.
Among the records submitted was the sale of an orange grove in 2003 for 66,111.33 euros, as well as the sale of securities in 2004 that yielded 34,692.22 euros. He also provided evidence of investment fund transactions and numerous cash withdrawals from his own accounts and from bank accounts belonging to his parents.
Some of the cash withdrawals documented by the pensioner dated back so far that they had been executed when the peseta was still Spain's official currency, before euro notes and coins entered circulation in 2002.
Tax authorities dismissed the paperwork, arguing that the documents failed to establish the specific origin of the cash deposited in 2017. Officials pointed out that several withdrawals were made from accounts belonging to third parties, did not identify who withdrew the money, and were separated from the 2017 deposit by periods of up to twenty years.
Legal ruling on unjustified capital gains
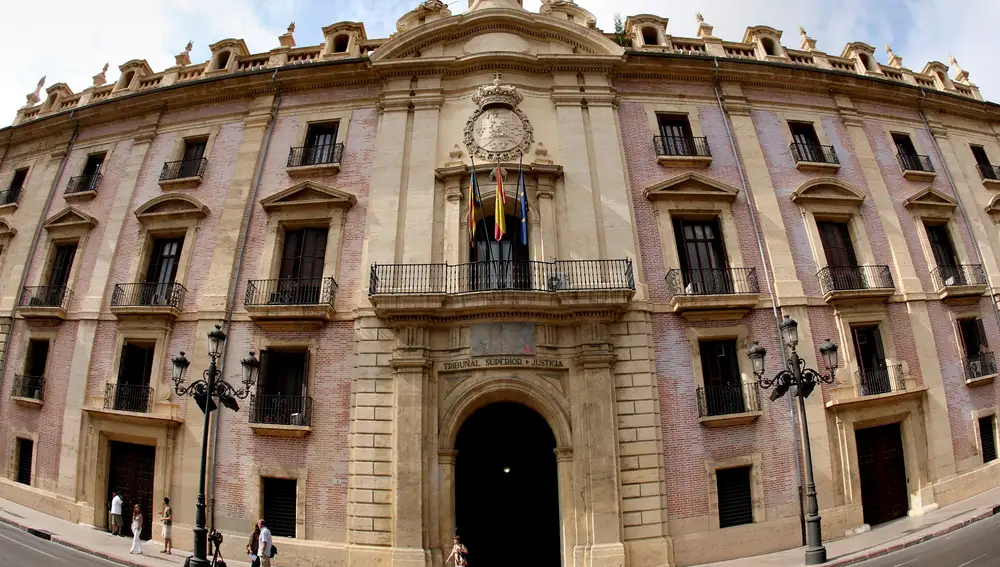
In Judgment 674/2025, delivered on 24 September 2025, the High Court of Justice of the Valencian Community reviewed the 2017 tax regularisation and affirmed the stance taken by the tax administration.
The judicial panel applied the rule set out in Article 39 of Spain's Personal Income Tax Law, known as the Ley del IRPF. The statute allows the tax agency to treat undeclared assets or cash as an unjustified capital gain attributed to the tax year in which they are discovered, unless the taxpayer can prove their lawful origin or establish ownership prior to the statutory limitation period.
The court held that proving historical income or remote cash withdrawals did not demonstrate that the banknotes deposited in 2017 were the same physical funds. Because the evidence did not trace the movement of the money from those remote transactions into the bank account, the judges upheld the full tax liability of 101,102.53 euros.
Cancellation of the financial penalty
While the court confirmed the tax assessment, it reached a different conclusion regarding the penalty. The magistrates ruled that imposing a fine requires proof of culpability and clear reasoning to substantiate the penalty, a legal burden that rests entirely on the tax agency.
The court found that the Agencia Tributaria had failed to prove the degree of culpability necessary to punish the taxpayer, and the judges therefore cancelled the 68,532.42 euro fine.
The appeal was partially upheld, confirming the tax debt while striking down the fine, with no express order regarding legal costs. The judgment was not final when delivered, leaving the parties a 30-day window from notification to prepare a cassation appeal before Spain's Supreme Court.


